How to Choose a Checking Account: Fees, Features and Fine Print
The everyday account you use most is also where small fees add up fastest. Here is what to compare.
Key takeaways
- Many good checking accounts have no monthly fee, or waive it with a direct deposit or minimum balance.
- Overdraft and insufficient-funds fees can be the most expensive part of an account; understand them before you open one.
- Check ATM access, cash deposit options and app features that match how you actually bank.
- Make sure your deposits are covered by deposit insurance.
A checking account (called a current account in the UK and many other countries) is the hub of your financial life: your salary arrives there, your bills leave from there, and your debit card draws on it. Because you use it every day, the right account saves you money and time, and the wrong one costs you both.
Step 1: Look at the monthly fee and how to avoid it
Some banks charge a monthly maintenance fee, often waived if you meet a condition such as a minimum balance, a minimum monthly direct deposit or a linked savings account. A $12 monthly fee costs $144 a year, which is more than many people earn in interest on their savings.
Ask yourself honestly whether you will meet the waiver condition every month. If not, a free account is the safer choice. Many online banks and credit unions offer accounts with no monthly fee at all.
Step 2: Understand overdraft rules
An overdraft happens when a payment takes your balance below zero. Banks handle this in different ways:
- Overdraft coverage: the bank pays the transaction and charges a fee per item.
- Insufficient-funds (NSF) fees: the payment is declined or returned, and you may still be charged.
- Overdraft transfers: money is moved automatically from a linked savings account, sometimes for a smaller fee.
- Arranged overdraft: common in the UK and Europe, this is a credit line on your account with an interest rate, often a high one.
Look for accounts with low or no overdraft fees, a small buffer, or the option to decline transactions that would overdraw your account. Low-balance alerts in the banking app help you avoid overdrafts altogether.
Step 3: Check fees you might actually pay
| Fee | What to check |
|---|---|
| ATM fees | Size of the free ATM network, fees for out-of-network use and whether the bank refunds other operators' fees |
| Foreign transactions | Fee for card payments in other currencies, often around 3%, and the exchange rate used |
| Wire and international transfers | Fees for sending and receiving, plus any exchange rate markup |
| Paper statements and checks | Some banks charge for paper statements or check books |
| Cash deposits | Whether and where you can deposit cash, and at what cost |
If you travel or shop in other currencies, read our guide to exchange rates and hidden currency fees.
Step 4: Compare features that fit your habits
- Mobile app quality: instant notifications, card freeze, spending insights and easy transfers.
- Payment options: mobile wallets, instant payment networks and person-to-person transfers.
- Early direct deposit: some accounts make your paycheck available up to two days early.
- Interest on balances: a few checking accounts pay interest, usually low. A separate savings account typically pays more.
- Joint accounts and sub-accounts for shared expenses or budgeting.
- Customer service: how easy it is to reach a real person when something goes wrong.
Step 5: Online bank, traditional bank or credit union?
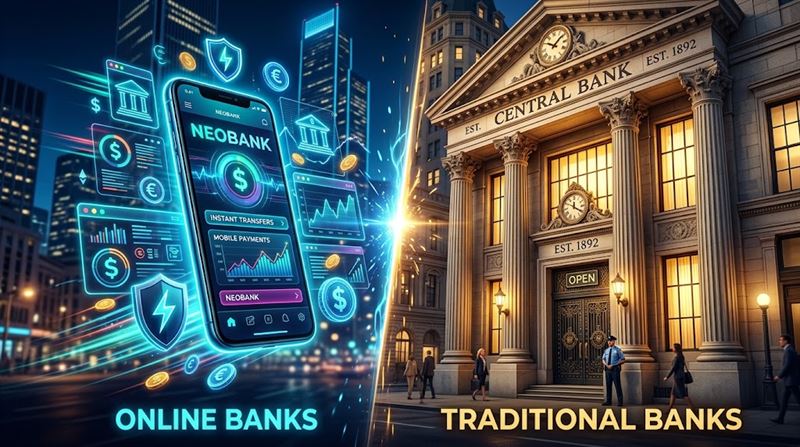
Online banks often have lower fees and better apps, but no branches and limited options for depositing cash. Traditional banks offer branches and in-person service, usually at a higher cost. Credit unions are member-owned and often combine low fees with personal service, but membership may be limited. We compare the options in detail in online banks vs. traditional banks.
Step 6: Confirm deposit protection
Make sure your money is protected by a deposit insurance scheme. In the US, look for FDIC insurance at banks or NCUA insurance at credit unions, each covering up to $250,000 per depositor, per institution, per ownership category. In the EU, the limit is €100,000 per depositor and bank. If you use a fintech app, check which licensed bank holds your money.
Switching accounts without stress
- Open the new account before closing the old one.
- Move your direct deposit and update automatic payments and subscriptions.
- Keep enough money in the old account for a month or two to catch payments you forgot.
- Close the old account in writing once it has been quiet for a full billing cycle.
Some countries, like the UK, have official switching services that move your payments for you. More in our checking account guides.