Online Banks vs. Traditional Banks: Which Is Right for You?
Rates, fees, service and safety compared, plus what to check before trusting a fintech app with your money.
Key takeaways
- Online banks typically offer higher savings rates and lower fees because they have no branch network to fund.
- Traditional banks provide branches, cash services and in-person advice, often at a higher cost.
- A licensed online bank is protected by the same deposit insurance as a traditional bank.
- Many fintech apps are not banks; check which partner bank holds your money.
Not long ago, choosing a bank meant choosing the branch closest to home. Today you can open an account in minutes on your phone with a bank that has no branches at all. Both models have real strengths, and many people end up using a combination.
How the two models differ
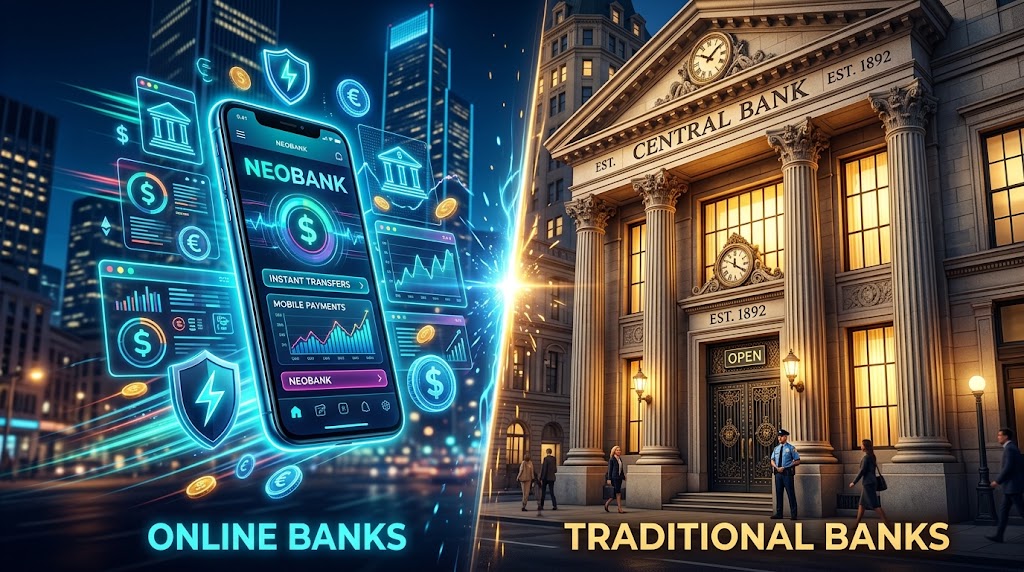
A traditional bank runs a network of branches and ATMs, employs staff for in-person service and usually offers the full range of products, from checking accounts to mortgages and business banking. An online bank (sometimes called a direct bank or digital bank) serves customers entirely through its app and website, with customer service by chat, phone or email.
Because branches are expensive, online banks can operate with lower costs. Many pass part of that saving on to customers through higher interest rates and fewer fees.
Side-by-side comparison
| Online banks | Traditional banks | |
|---|---|---|
| Savings rates | Often well above average | Often lower, especially on standard accounts |
| Account fees | Frequently none | Monthly fees common, with waiver conditions |
| Branches | None | Yes, for in-person service |
| Cash deposits | Limited or via partner networks | Easy at branches and ATMs |
| Digital tools | Usually strong, app-first | Varies widely |
| Product range | Often focused on core accounts | Broad: loans, mortgages, business, advice |
| Complex problems | Handled remotely | Can be solved face to face |
When an online bank makes sense
- You want a competitive rate on your savings or emergency fund.
- You rarely handle cash and are comfortable managing everything in an app.
- You want to avoid monthly fees on your checking account.
- You travel and want low foreign transaction fees and instant card controls.
When a traditional bank makes sense
- You regularly deposit cash, for example from a small business.
- You value in-person service for complex matters such as a mortgage or an estate.
- You want several products, such as checking, savings, loans and investments, in one relationship.
- You need services like certified checks, safe deposit boxes or notary services.
A popular combination is a traditional bank for everyday checking and cash, plus an online bank for higher-yield savings. Transfers between the two usually take one to three business days, so keep enough in your everyday account for upcoming bills.
Is an online bank safe?
Safety depends on regulation, not on whether a bank has branches. A licensed online bank is supervised by the same regulators and covered by the same deposit insurance as a traditional bank. In the US, FDIC insurance covers up to $250,000 per depositor, per insured bank, for each account ownership category, and you can verify a bank with the FDIC's BankFind tool. In the EU, deposits are protected up to €100,000 per depositor and bank; in the UK, the Financial Services Compensation Scheme (FSCS) protects eligible deposits at authorized banks.
Two details are worth checking:
- Brand names: some banks operate several online brands under one banking license. Deposits across those brands may count toward a single insurance limit.
- Cross-border banks: a bank licensed in another country is covered by that country's scheme, not yours.
Fintech apps are not always banks
Many money apps look like banks but are technically payment or e-money companies that partner with a licensed bank. Depending on the structure and the country, your money may be held at the partner bank with deposit insurance passing through to you, or it may be safeguarded under e-money rules, which is a different protection that does not work like deposit insurance.
Before you move significant savings to an app, check its terms for the name of the partner bank and the exact type of protection. Look for phrases such as "banking services provided by" in the app's legal information.
How to compare banks
- Confirm the license and deposit protection.
- Compare rates and all fees you are likely to pay, including ATM and foreign transaction fees.
- Test the app and look at independent reviews of customer service.
- Check how easily you can deposit cash and transfer money to other banks.
- Consider which other products you might need in the future.
More guides in our banking section.