Assumable Mortgages: How to Take Over a Seller's Low Rate (FHA, VA, USDA)
Which mortgages can be assumed, how much a low assumed rate saves at 2026 rates, the equity gap you must cover, VA entitlement and release of liability, fees and the steps of an assumption.
Listen to this article
Key takeaways
- FHA, VA and USDA loans are assumable with lender approval; most conventional loans are not because of due-on-sale clauses.
- Taking over a $280,000 loan at 3% instead of a new loan at 7.28% saves about $588 a month.
- You must pay the seller their equity, the gap between price and loan balance, in cash or with a second loan.
- Fees are modest: FHA assumption fees are capped at $1,800, and VA charges a 0.5% funding fee.
Millions of homeowners hold mortgages from years when rates were far lower than today. An assumable mortgage lets a buyer step into that loan, keeping the original rate, remaining balance and maturity date. It is one of the few ways to buy a home in 2026 at a rate from 2021, but it comes with conditions that make it work only for some buyers.
Please note
General information as of October 2026. The servicer must approve every assumption, and processing times can be long. Sellers should get legal advice on release of liability.
Which mortgages can be assumed
| Loan type | Assumable? | Key conditions |
|---|---|---|
| FHA | Yes | Buyer must qualify; assumption fee capped at $1,800; FHA mortgage insurance continues |
| VA | Yes | Buyer qualifies with the servicer; 0.5% funding fee unless exempt; entitlement rules (see below) |
| USDA | Yes | Buyer must meet USDA eligibility, including income and property location |
| Conventional | Generally no | Due-on-sale clause; limited exceptions such as transfers to a spouse or child |
How much an assumption saves
Suppose the seller owes $280,000 at 3.0% with 25 years left. A new 30-year loan for the same amount at the October 1, 2026 average of 7.28% would cost:
| Monthly principal and interest | |
|---|---|
| Assumed loan, 3.0%, 25 years left | $1,327.79 |
| New loan, 7.28%, 30 years | $1,915.79 |
| Difference | $588.00 |
The assumed loan also pays off five years sooner, since its remaining term is shorter.
The catch: the equity gap
You take over the balance, not the price. If the home sells for $400,000 and the seller owes $280,000, you must pay the seller $120,000. Options:
- Cash from savings or the sale of your current home.
- A second mortgage or HELOC from a lender willing to lend behind the assumed loan, typically at a higher rate on that portion.
- Seller financing for part of the gap, if the seller agrees.
Even with a higher-rate second loan, the blended rate can be well below a new mortgage. Calculate the combined payment before you commit.
VA assumptions: entitlement and liability
When a VA loan is assumed, the VA charges the buyer a funding fee of 0.5% of the balance (exemptions exist, for example for veterans receiving compensation for service-connected disabilities). For the seller, two issues matter:
- Entitlement: if the buyer is not a veteran, the seller's VA entitlement stays tied to the loan until it is paid off, which can limit the seller's ability to use a VA loan again. If the buyer is an eligible veteran who substitutes their own entitlement, the seller's entitlement is restored.
- Release of liability: the seller should obtain a formal release; otherwise they could remain liable if the buyer defaults.
The assumption process
- Confirm the loan type and ask the seller's servicer whether it accepts assumptions.
- Apply with the servicer; it checks your credit, income and debts much like a new loan.
- Arrange financing for the equity gap.
- Close, pay the assumption fee, and make sure the seller receives a release of liability.
Assumptions can take longer than a regular purchase, often 45 to 90 days or more, so build that into the contract timeline.
Is an assumable mortgage right for you?
- Good fit: you have substantial cash or equity from a sale, the seller's rate is far below market and the home suits you for years.
- Poor fit: you have little cash, the equity gap is large, or you need to close quickly.
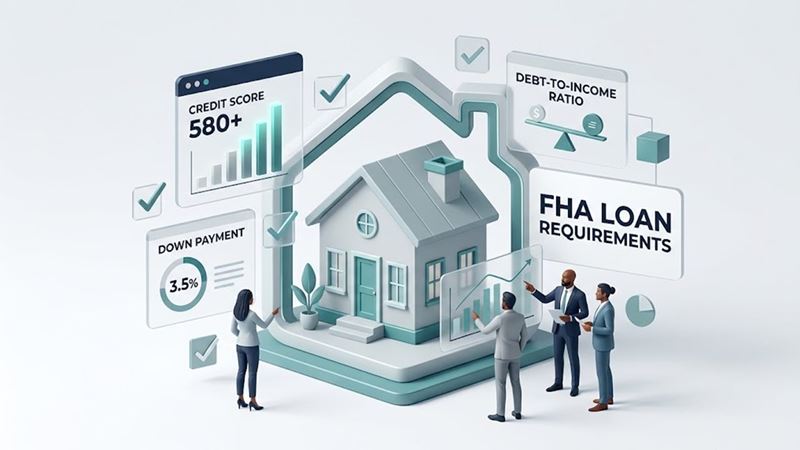
Buyers with small down payments may be better served by the programs in our first-time home buyer guide. Details on FHA mortgage insurance, which continues after an assumption, are in FHA loan requirements.
Frequently asked questions
Can anyone assume an FHA loan?
The buyer must qualify with the servicer based on credit and income. Investors generally cannot assume FHA loans for non-owner-occupied use.
Do I need to be a veteran to assume a VA loan?
No. Non-veterans can assume VA loans if they qualify, but the seller's entitlement then remains tied to the loan.
Are conventional mortgages ever assumable?
Rarely. Most contain a due-on-sale clause; federal law allows certain transfers, for example to a spouse or child, without triggering it.
How do I find homes with assumable loans?
Ask listing agents, look for "assumable" in listing remarks, or use services that track government-backed loans on listed homes.
Does an assumption appear on my credit report?
Yes. Once approved, the loan is reported in your name like any other mortgage.