FDIC Insurance Limits Explained: How to Protect More Than $250,000
What the $250,000 limit really applies to, how ownership categories multiply coverage, the 2024 trust rule that covers up to $1.25 million per owner, credit union insurance and what is not covered.
Listen to this article
Key takeaways
- The standard limit is $250,000 per depositor, per insured bank, per ownership category.
- Joint accounts are insured up to $250,000 per co-owner, so $500,000 for a couple.
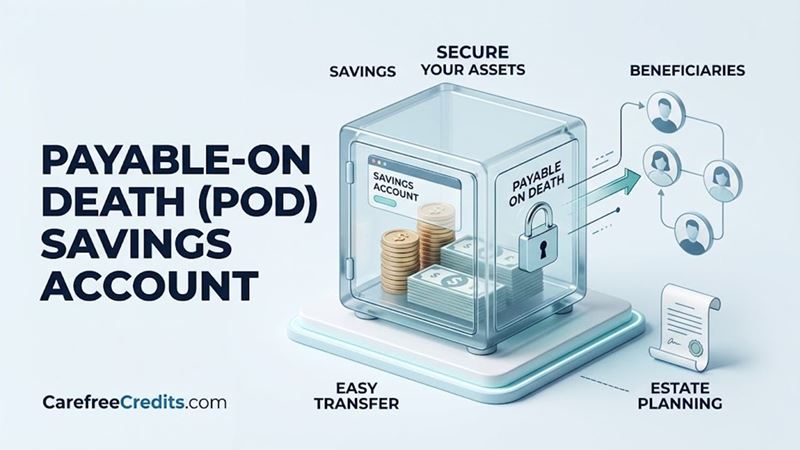
- Since April 1, 2024, trust accounts, including payable-on-death accounts, are insured up to $250,000 per beneficiary, for up to five beneficiaries: $1.25 million per owner per bank.
- Stocks, bonds, mutual funds, crypto and annuities are not FDIC insured, even if bought at a bank.
Since 1934, no depositor has lost a penny of FDIC-insured funds. The guarantee is strong, but its limits are often misunderstood: they apply per bank and per ownership category, not per account. Knowing how the categories work lets you protect large balances without spreading money across a dozen banks.
Please note
Based on FDIC rules as of October 2026. For an exact calculation of your coverage, use the FDIC's Electronic Deposit Insurance Estimator (EDIE) or call the FDIC.
What is and is not covered
| Insured (deposits) | Not insured |
|---|---|
| Checking and savings accounts | Stocks, bonds and mutual funds, including money market funds |
| Money market deposit accounts | Annuities and life insurance |
| Certificates of deposit | Crypto assets |
| Cashier's checks and money orders issued by the bank | Safe deposit box contents |
Insurance applies only if the bank fails. It does not cover fraud on your account; separate laws such as Regulation E limit liability for unauthorized electronic transfers.
The ownership categories
| Category | Coverage |
|---|---|
| Single accounts | $250,000 per owner (all single accounts at the bank combined) |
| Joint accounts | $250,000 per co-owner |
| Certain retirement accounts (IRAs, self-directed plans) | $250,000 per owner |
| Trust accounts (revocable, irrevocable, POD) | $250,000 per owner per beneficiary, up to five beneficiaries ($1.25 million per owner) |
| Business accounts (corporations, partnerships, LLCs) | $250,000 per entity |
| Employee benefit plan and government accounts | Separate rules |
Examples at one bank
A married couple
- Each spouse's single account: $250,000 + $250,000
- Joint account: $500,000
- Each spouse's IRA deposits: $250,000 + $250,000
- Each spouse's payable-on-death account naming their three children: $750,000 + $750,000
Total potential coverage at one bank: $3.0 million, if each account is titled correctly.
Beneficiary designations are explained in payable-on-death savings accounts.
FDIC vs. NCUA: how credit union deposits are protected
Federally insured credit unions are covered by the National Credit Union Share Insurance Fund, administered by the NCUA, with the same standard $250,000 limit per member, per credit union, per ownership category. Rules for joint, retirement and trust accounts are similar but not identical to the FDIC's, so check the NCUA's own estimator for complex arrangements.
| FDIC | NCUA | |
|---|---|---|
| Covers | Deposits at insured banks and savings associations | Shares and deposits at federally insured credit unions |
| Standard limit | $250,000 per depositor or member, per institution, per ownership category | |
| Backing | Full faith and credit of the U.S. government | |
| Funded by | Premiums paid by banks | Deposits and premiums from credit unions |
| How to check | FDIC BankFind | NCUA Credit Union Locator |
In practice the protection is equivalent: no depositor has lost a penny of insured funds at an FDIC-insured bank since the FDIC began in 1934, and NCUA-insured members have the same government guarantee. A small number of credit unions are privately insured instead; their branches and websites must say so. For how the two kinds of institutions differ beyond insurance, see bank vs. credit union.
Fintech apps and brokerage sweeps
Many apps and brokerages place your cash at one or more partner banks. You are insured only if the money is actually held at an insured bank in a way that identifies you as the owner, and only up to the limits at each bank. Some programs spread money across many banks to offer coverage beyond $250,000. Read the disclosures, and remember that the app itself is not insured if it fails. See the fintech caution in high-yield savings accounts.
Ways to insure more than $250,000
- Use ownership categories at one bank, as in the example above.
- Spread deposits across banks; coverage applies separately at each insured bank. Check that two brands are not the same bank under one charter.
- Use a deposit placement network offered by some banks, which places funds at multiple banks in increments under the limit.
- Consider Treasury bills for very large cash balances; they are backed by the U.S. government rather than deposit insurance.
How to check whether your bank is insured
Use the FDIC's BankFind tool, look for the FDIC sign at the bank, and check the legal bank name on your account documents. Online-only brands often operate under a separate brand name of a chartered bank.
Frequently asked questions
Is the FDIC limit $250,000 per account?
No, per depositor, per bank, per ownership category. Two single accounts in your name at the same bank share one $250,000 limit.
How much is a joint account insured?
$250,000 per co-owner, so $500,000 for a joint account of two people, separately from their single accounts.
Are CDs FDIC insured?
Yes, CDs at insured banks are deposits and count toward the same limits.
What happens if my bank fails?
The FDIC typically pays insured deposits within a few business days, often by transferring accounts to another bank.
Are money market funds FDIC insured?
No. They are investments. Money market deposit accounts at banks are insured.