Money Market Account vs. Savings Account (and Money Market Funds)
How money market accounts differ from savings accounts, why a money market fund is a different product altogether, what each pays in 2026, how safe each is and which one fits which job.
Listen to this article
Key takeaways
- A money market account (MMA) is a bank or credit union deposit account, insured up to $250,000, often with checks or a debit card.
- A money market fund (MMF) is a mutual fund that invests in short-term debt. It is not FDIC insured, though it aims to keep a stable value.
- National averages in September 2026 (FDIC): savings 0.37%, money market accounts 0.63%; competitive accounts pay far more.
- For an emergency fund, an insured high-yield savings or money market account is the usual base; an MMF can serve as a second tier.
The names cause real confusion. A money market account and a money market fund sound alike, but one is a bank deposit and the other is an investment. Savings accounts and money market accounts, by contrast, are close cousins that differ mainly in access and minimums.
Please note
Rates as of September and October 2026 and subject to change. A money market fund's yield is not guaranteed, and past yields do not predict future ones.
The three products side by side
| Savings account | Money market account | Money market fund | |
|---|---|---|---|
| What it is | Bank deposit | Bank deposit | Mutual fund (investment) |
| Where you open it | Bank or credit union | Bank or credit union | Brokerage or fund company |
| Insurance | FDIC/NCUA up to $250,000 | FDIC/NCUA up to $250,000 | No FDIC; SIPC covers brokerage failure, not losses |
| Return | Variable APY | Variable APY, sometimes tiered by balance | Variable yield (7-day SEC yield) |
| Access | Transfers, sometimes ATM | Often checks and a debit card | Sell shares, usually settled the next business day |
| Minimums | Often none | Sometimes higher | Low at most brokerages |
Money market account vs. savings account
Both are insured deposits with variable rates. Differences tend to be practical:
- Access: money market accounts more often include check-writing or a debit card.
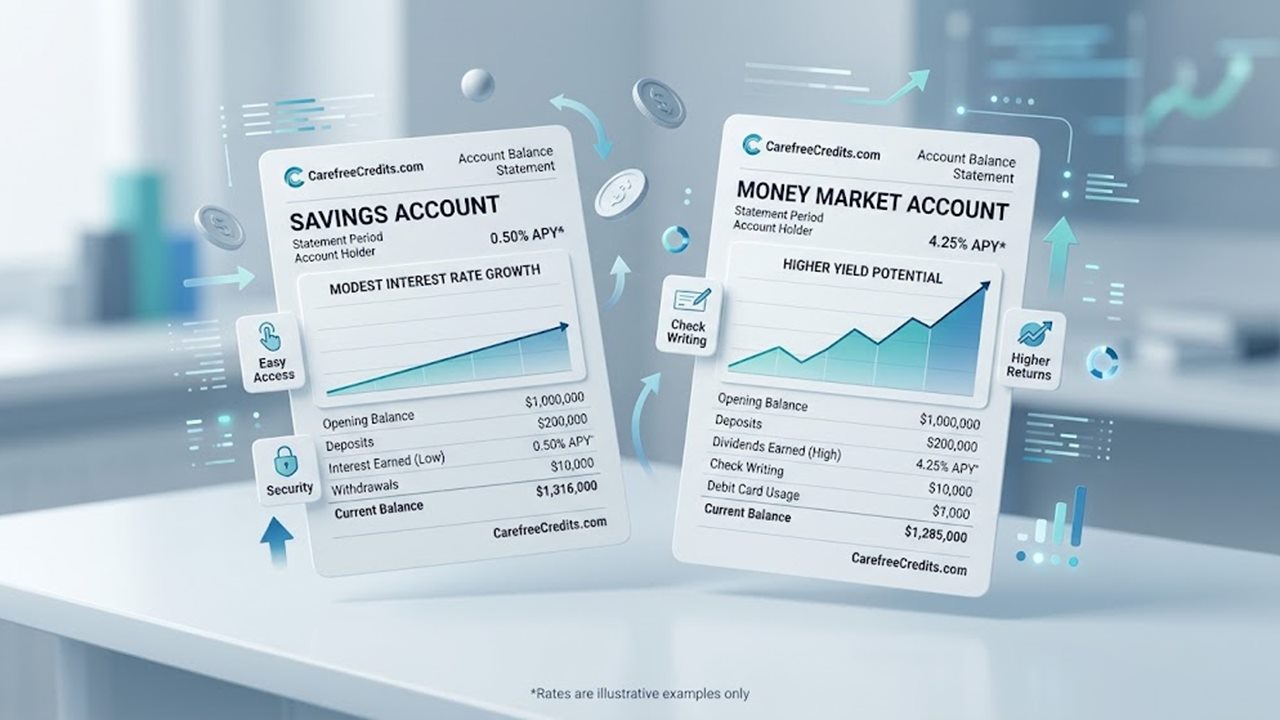
- Rates: nationally, MMAs averaged 0.63% vs. 0.37% for savings in the FDIC's September 2026 survey. At competitive online banks, the two often pay similar rates.
- Minimums and tiers: some MMAs pay the best rate only above a balance threshold or charge a fee below a minimum.
If you do not need checks, a high-yield savings account with no minimums is often the simpler choice.
High-yield savings vs. money market account
When people compare the best savings options, the real choice is usually between a high-yield savings account at an online bank and a competitive money market account. Both are FDIC- or NCUA-insured deposits with variable rates, and in early October 2026 leading offers of both types paid around 4%, far above the national averages of 0.37% and 0.63%.
| High-yield savings account | Money market account | |
|---|---|---|
| Typical rate | Competitive online banks around 4% (early October 2026) | Similar at competitive banks; often tiered by balance |
| Minimum balance | Often none | Sometimes $1,000 or more for the best rate or to avoid a fee |
| Checks and debit card | Rarely | Often |
| Withdrawal limits | Some banks limit to six per month | Same; some banks limit withdrawals |
| Best for | Emergency funds and goals with no need for checks | Larger balances you occasionally pay bills from |
Pick the one with the higher APY after fees for your balance. If you write a few large checks a year, for example for property taxes or tuition, a money market account saves a transfer step. To see what each would earn, use the savings account calculator.
What a money market fund is
A money market fund invests in very short-term, high-quality debt such as Treasury bills, government agency debt and repurchase agreements. Funds regulated under the SEC's Rule 2a-7 must meet strict limits on credit quality, maturity and liquidity. Government money market funds, which invest almost entirely in government securities, typically seek a stable $1.00 share price. Their yields usually move closely with short-term Treasury rates and the Fed's policy rate, which was 3.75% to 4.00% after September 16, 2026.
The trade-off is protection: a money market fund is not a deposit and is not FDIC insured. Breaking the $1.00 share price is rare but has happened, most notably in 2008. SIPC protection at a brokerage covers missing securities if the broker fails, not a decline in a fund's value.
Taxes
- Interest from savings and money market accounts is taxed as ordinary income and reported on Form 1099-INT.
- Money market fund income is paid as dividends, reported on Form 1099-DIV, and taxed as ordinary income.
- Treasury-focused money market funds can be partly exempt from state income tax, depending on how much of their income comes from U.S. government obligations and your state's rules.
More in is savings account interest taxable?
Which to use for what
| Goal | Good fit |
|---|---|
| Emergency fund | High-yield savings or money market account |
| Paying large bills by check from savings | Money market account |
| Cash waiting to be invested in a brokerage account | Money market fund |
| Balances above deposit insurance limits | Additional banks, ownership categories or a Treasury money market fund |
How deposit insurance works across ownership categories is explained in FDIC insurance limits.
Frequently asked questions
Is a money market account FDIC insured?
Yes, at an FDIC-insured bank, up to $250,000 per depositor, per bank, per ownership category. At a credit union, NCUA insurance provides the same coverage.
Is a money market fund safe?
Money market funds are among the lowest-risk investments, but they are not insured. Government money market funds carry the least credit risk.
Which pays more, a money market account or a savings account?
On national averages, money market accounts pay slightly more. Among competitive online banks, rates are often similar; compare actual offers.
Can I lose money in a money market account?
Not as long as your balance is within insurance limits at an insured institution. You can lose purchasing power if inflation exceeds your rate.
Are there withdrawal limits on money market accounts?
The federal six-per-month limit was removed in 2020, but banks may still set their own limits; see savings withdrawal limits.