Tools
Free Amortization Schedule Calculator: Monthly Payment Table
Create a full month-by-month amortization schedule for any loan, see how each payment splits into principal and interest and how extra payments shorten the loan.
The advertised rate is only part of the price. These guides break down fees, terms and interest methods so you can compare loans on total cost.
14 guides about “Loan Costs”.
Create a full month-by-month amortization schedule for any loan, see how each payment splits into principal and interest and how extra payments shorten the loan.
Enter the amount, rate and term to see your monthly payment, total interest and APR including fees. Add an extra payment to see how much time and interest you save, and download the full schedule.
Pay-in-four plans are usually interest-free, but late fees, stacking several plans and longer financing at up to 36% APR can get expensive. Some BNPL loans now show up on credit reports and in newer scores.
Closing costs usually run about 2% to 5% of the loan amount on top of the down payment. Here is what they include, how to estimate yours and how to bring the total down.
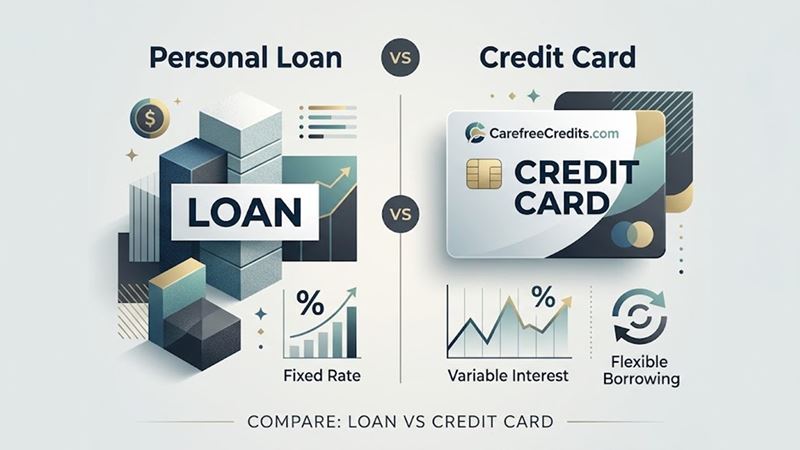
Personal loans usually charge far less interest than credit cards and have a fixed end date, while cards win for short-term borrowing, 0% offers and flexibility. Here is how to choose.
When property taxes or insurance rise, your escrow account comes up short and the servicer raises your payment. Federal rules limit the cushion to two months and let you spread a shortage over 12 months.
A mortgage recast keeps your rate and term but recalculates the payment after a lump-sum principal payment, usually for a fee of a few hundred dollars. Here is when it beats refinancing and when it does not.
Service members can cap interest at 6% on debts taken out before active duty under the SCRA, and the Military Lending Act limits most new consumer credit to a 36% MAPR. Here is who qualifies and how to claim it.
Payday alternative loans let federal credit union members borrow $200 to $2,000 at no more than 28% interest plus a fee of at most $20. Learn the PAL I and PAL II rules and what they cost compared with a payday loan.
Under the Rule of 78, interest is front-loaded, so paying a loan off early saves less than you expect. Federal law bans it for consumer loans longer than 61 months. Here is how it works and how to check your contract.
In Q2 2026, new car loans averaged 6.35% and used car loans 11.19%, but borrowers with top credit paid about a quarter of what subprime borrowers paid. See the full table and what each rate costs.
A debt consolidation loan replaces several card balances with one fixed payment. With card APRs averaging 22.15%, it can save thousands, but only if the new loan is cheaper and the cards stay paid down.